Federal Scholarship Tax Credit Benefit
Offer a New Tax Credit Benefit With Minimal Administrative Burden
Starting January 1, 2027, employers can offer their employees a new payroll deduction benefit tied to the Federal Scholarship Tax Credit (FSTC), a new federal scholarship tax credit program that supports K-12 scholarship funding. Employees can direct a portion of their paycheck to an eligible Scholarship Granting Organization (SGO) and receive up to $1,700 back as a federal tax credit. BenefitEd simplifies administration by connecting employee enrollment, payroll deduction, and reporting through a centralized platform.
Organizations can:
- Offer a distinctive voluntary benefit.
- Support employee engagement and community impact.
- Help employees spread a monetary contribution over time through payroll deduction.
- Provide employees with simplified access to a unique federal tax credit opportunity.
- Demonstrate a commitment to education and community impact.
Starting Jan. 1, 2027, individuals can contribute to approved Scholarship Granting Organizations (SGOs) in states that choose to participate and receive that same amount back as a dollar-for-dollar federal tax credit — up to $1,700 per taxpayer, per year ($3,400 for married couples filing jointly). This federal scholarship tax credit program is also known as the Education Freedom Tax Credit (EFTC) and was enacted into law as the Educational Choice for Children Act (ECCA). BenefitEd’s platform makes giving as simple as offering a payroll election option to your employees that lets them take advantage of this tax credit.
Who Is This Benefit Right For?
Whether you’re a company, nonprofit, or educational institution, offering the Federal Scholarship Tax Credit benefit to employees looks a little different.
Boost Education Giving
Allow employees to support scholarship funding that benefit students in their communities.
High Impact, Low Lift
Offer high-impact benefit with minimal administrative burden.
Easy to Administer
Provide a new employee benefit without managing a separate manual process.
Give and Get Back
Support educational opportunities while receiving a dollar-for-dollar federal tax credit.
How the Benefit Works
Employee Selects an SGO to Support
Employees choose a Scholarship Granting Organization (SGO) to support — often based on its mission or community, since by law every SGO funds students across multiple schools. The SGO must be listed by a state that has opted in to the FSTC. If an employee’s own state hasn’t opted in yet, they can still contribute to a qualifying SGO in a state that has.
Employee Elects a Payroll Deduction
Employees log in to the company's BenefitEd portal, where they choose an SGO and school they'd like to support, along with their annual contribution amount. That amount spreads automatically across each paycheck based on the employer's payroll cycle. Employees can also adjust their W-4 withholding — BenefitEd coordinates with their employer — to help offset the paycheck impact.
BenefitEd Securely Transfers Funds
BenefitEd's platform connects securely with your HR and payroll systems through an encrypted file transfer or API connection to process each employee's payroll deduction and route funds to their selected SGO. Every transaction is tracked, giving your HR team a clear reporting and audit trail.
SGO Awards Scholarships
The SGO reviews applications and awards scholarships to eligible students. Federal rules require priority go first to students continuing a scholarship from the year before, then their siblings — protecting continuity for families already relying on the program. Beyond that, the SGO awards remaining scholarships to newly eligible students as funding allows.
Employee Claims the Tax Credit
Employees receive a receipt from their SGO documenting their total contribution for the year, which they use when filing taxes. They can then claim a dollar-for-dollar federal credit for what they contributed, up to $1,700 — reducing what they owe. If the credit is more than they owe, the unused portion carries forward for up to five years.
Key Federal Scholarship Tax Credit Facts

Credit Value
Up to $1,700 per taxpayer, per year ($3,400 for married couples filing jointly) — dollar-for-dollar, nonrefundable
Effective Date
Contributions made on or after Jan. 1, 2027
Eligibility for a Scholarship Tax Credit
Household income at or below 300% of the area median gross income
SGO Spending Rule
At least 90% of contributions go directly to scholarships
State Availability
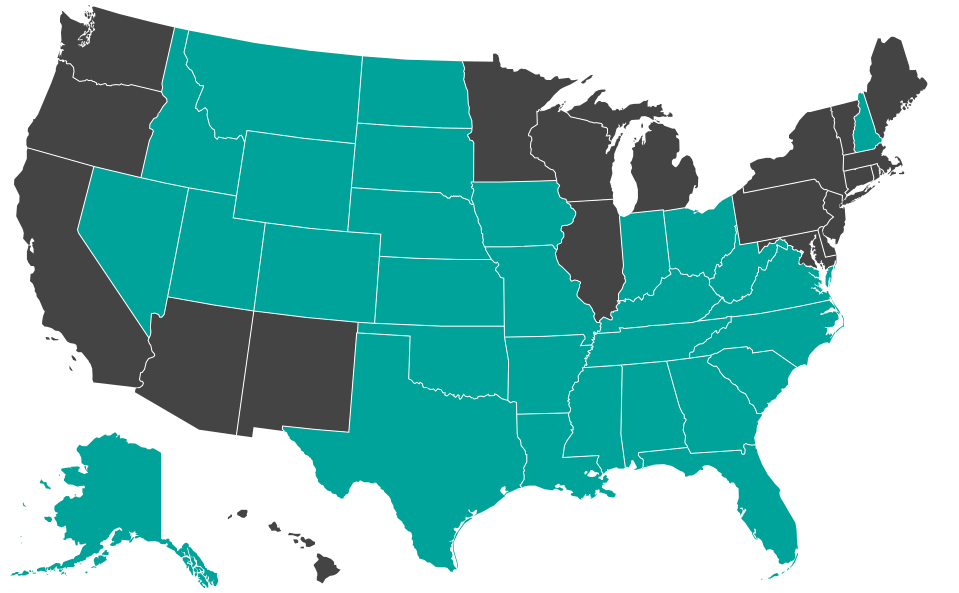
Any U.S. taxpayer can claim this credit, regardless of where they live. What varies by state is which SGOs, and the students they support, are eligible: each state must opt in annually before its SGOs can accept credit-eligible contributions. This list reflects the states currently certified — check back, as it may grow throughout the year.
Because every contribution flows through an SGO, it helps to understand exactly what one is and what it’s required to do.
The SGO’s Role in Administering the FSTC
A Scholarship Granting Organization (SGO) is the certified nonprofit at the center of the program, collecting contributions and awarding scholarships to eligible K-12 students. By law, an SGO must serve students across more than one school and can’t earmark funds for a specific student — though some allow donors to recommend a specific school. SGOs must direct at least 90% of contributions to student scholarships, capping their own administrative costs at 10%.
SGOs can support private faith-based schools, public schools, and charter schools. Home school and hybrid learning students may also qualify, though eligibility depends on whether their state legally defines homeschooling as a school — not all states do.
How FSTC Scholarship Funds Support Students
Schools and educational institutions.
Employers seeking innovative voluntary benefits.
Organizations looking for low-administration benefit options.
Employers interested in promoting employee community impact.
How Policy Supports FSTC
The Educational Choice for Children Act established the framework for the Federal Scholarship Tax Credit. Section 70411 of the One Big Beautiful Bill Act added IRC Section 25F to the Internal Revenue Code, creating the federal tax credit for qualifying contributions to approved Scholarship Granting Organizations. As regulatory guidance continues to develop, understanding this foundation can help employers prepare to offer the benefit.
BenefitEd helps employers navigate applicable policies and regulations, understand tax advantages, and design programs that align with current and evolving requirements.
Frequently Asked Questions
Build a More Complete Benefits Strategy
The Federal Scholarship Tax Credit benefit works alongside other education and financial wellness offerings to support employee engagement, community involvement, and long-term educational goals.
Organizations often pair this benefit with:



Together, these programs help organizations support employees at different stages of their educational and financial journeys.
See How the Federal Scholarship Tax Credit Benefit Could Work for Your Organization
This benefit is new, and BenefitEd can help you understand how payroll deductions, employee participation, and program administration fit within your organization’s goals.
Disclaimer: This page is for general informational purposes only and does not constitute tax, legal, or financial advice. Tax laws and regulations are subject to change, and individual circumstances vary. Consult a qualified tax advisor or financial professional regarding your specific situation.